Europe’s Gas Buffer Hits 15-Year Low as Iran War Raises Winter Risk
By SKAAH Media Webdesk, Newsroom
· 3 min read
AI Summary
Europe enters winter with the lowest gas storage in 15 years as the Iran conflict disrupts Qatari LNG supply, leaving the bloc exposed to cold-weather shortages and price spikes.
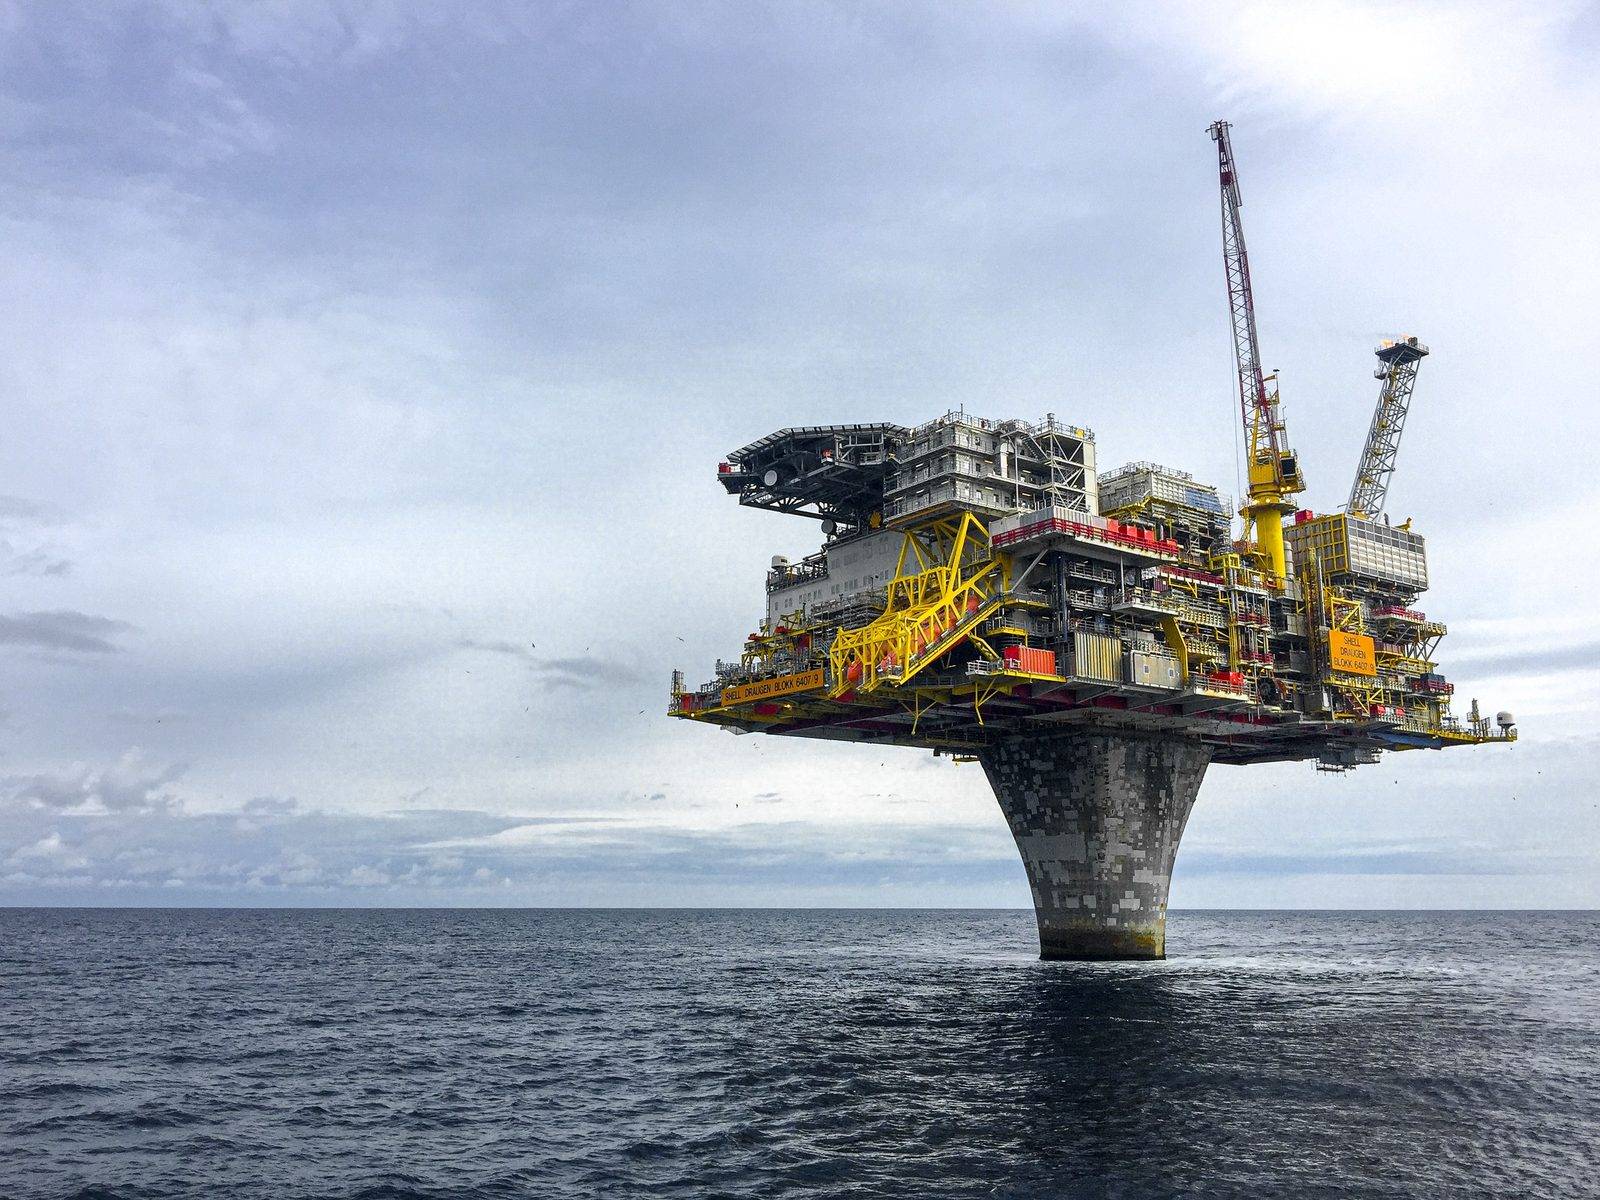
Europe is approaching the 2026-27 heating season with the most limited gas reserves seen in fifteen years, a situation exacerbated by the disruptions to Middle Eastern supply routes associated with the Iran conflict.
As of 1 November, EU storage levels reached 74.6%, marking the lowest seasonal figure recorded since 2011. This is significantly below the average of 90.5% for this date, as reported by Gas Infrastructure Europe and referenced by Newsbase.
The benchmark Dutch TTF contract, which surpassed €100 per megawatt-hour in October, was trading around €96/MWh on 2 November, approximately 2.6 times its value from a year prior.
Germany’s 61% Fill Level Exposes Bloc’s Weakest Link
The decline came from a high of precisely 74.96% on 27 October. Germany, being the largest consumer in the bloc, began the season at around 61% capacity, a situation that has already tested relations with Italy and constrained Berlin's options if temperatures dip below the usual levels.
The regulations set by the EU allow for a storage target as low as 80% under the flexibility provisions activated in March. However, this lowered benchmark is now unattainable as withdrawals continue to take place.
The disruption on the supply side can be attributed to the significant blockage of the Strait of Hormuz, which occurred after military actions by the US and Israel against Iran in late February.
Qatari LNG exports via the strait faced interruptions, eliminating a vital source of adaptable shipments at a time when Europe was aiming to replenish its inventories following a challenging summer.
Goldman Sachs has projected that a frigid winter might drive TTF prices to €150/MWh, a situation that could exacerbate industrial cutbacks and household debt throughout the region.
EU Storage at 74.6% as TTF Holds Near €96
Market indicators are already suggesting a decline in demand. On November 5, the chief financial officer of Engie reported a significant decline in industrial gas consumption during the third quarter, indicating that this trend is expected to persist throughout the winter.
Energy-intensive sectors, particularly chemicals, are anticipated to experience the most considerable challenges.
German electricity prices have risen alongside petrol prices, as low wind generation compelled utilities to rely on gas-fired power generation just as fuel costs spiked.
The role of petrol in determining pricing within the power system indicates that electricity costs are influenced by fuel prices, even when renewable sources provide the majority of the supply.
The political ramifications of the crisis are manifesting in a disparate manner. Since March, Spain has allocated approximately €12 billion in support measures, whereas France has opted for targeted interventions in the lead-up to April’s presidential election.
This decision has faced backlash from opposition parties and has sparked street protests concerning the rising cost of living.
Italy, reliant on imported petrol, is under increasing pressure from transporters and manufacturers for more extensive support.
The European Commission has stood firm against requests to postpone the complete ban on Russian LNG imports set for 1 January, asserting that the phase-out is a matter of security rather than a factor influenced by market conditions.
Cold Spell Could Test Demand-Cut Plans
The weather continues to be the critical factor in the short term. Predictions have largely indicated a winter that will be less severe than usual, yet the scope for inaccuracies remains limited.
ENTSOG modelling indicates that during a frigid winter with constrained LNG supply, EU storage levels could decline to 11% by spring, reaching the threshold of remaining strategic reserves, despite the implementation of demand restraint measures.
A single extended cold wave in northwest Europe would compel buyers to go with Asian importers for immediate shipments in a market where the price difference between summer and winter has already diminished, deterring early stockpiling.
Currently, the market reflects a geopolitical risk premium that has the potential to dissipate just as swiftly as it was established.
On 2 November, TTF experienced a decline of over 3% following indications from Iranian President Masoud Pezeshkian that Supreme Leader Mojtaba Khamenei had given the green light for discussions with Washington.
However, the physical balance continues to be constrained. Europe currently holds approximately one-sixth less gas than the typical levels, and the infrastructure flexibility that previously mitigated shocks has diminished due to low hydro reserves and a decreasing number of dispatchable backup plants.
The continent may navigate a mild winter with ease, but it cannot withstand the harshness of a cold one through sheer force.
(Edited by Rahul Karunakar; rahul.karunakar@skaah.media)
Comments
Comments are not open on this story. Join the conversation by sharing it, or write to our editors.